Quarterly Economic Update: October to December 2025
The December quarter has been defined by unexpected twists. Just as we thought inflation was under control, it kicked back up. Just as rate cuts seemed certain for 2026, we’re…


The December quarter has been defined by unexpected twists. Just as we thought inflation was under control, it kicked back up. Just as rate cuts seemed certain for 2026, we’re…
There’s a growing issue facing families today, and it spans three generations. At the heart of it is the younger generation—the first-time homebuyers—who are struggling to break into the property market. This challenge isn’t just theirs to bear; it’s one that also involves their parents and grandparents, who want to see them succeed but are grappling with how to provide the right kind of support without overstepping or creating dependency.
Talking to children about money can sometimes feel awkward, but the truth is they are learning from us every day. The way we spend, save, and talk about money shapes their attitudes well into adulthood. By teaching kids healthy money habits early, we give them confidence and skills that will last a lifetime.
There’s a growing issue facing families today, and it spans three generations. At the heart of it is the younger generation—the first-time homebuyers—who are struggling to break into the property market. This challenge isn’t just theirs to bear; it’s one that also involves their parents and grandparents, who want to see them succeed but are grappling with how to provide the right kind of support without overstepping or creating dependency.
Money is one of the most common sources of stress in relationships. Whether it is with a partner, family member, or even a business partner, the way we think about and manage money can have a big impact on how we relate to each other.
There’s a growing issue facing families today, and it spans three generations. At the heart of it is the younger generation—the first-time homebuyers—who are struggling to break into the property market. This challenge isn’t just theirs to bear; it’s one that also involves their parents and grandparents, who want to see them succeed but are grappling with how to provide the right kind of support without overstepping or creating dependency.
Many Australians find themselves in what is called the “sandwich generation.” This is the stage of life where you may still be supporting children while also stepping in to care for ageing parents. It can feel like you are being pulled in two directions, both emotionally and financially.
From early November retailers have been telling us what we can’t live without and what our kids must have if they are to still love us on Christmas Day. It’s easy to get caught up in the momentum. Of course, the downside is you end up with the post-Christmas blues when the credit card statements arrive. This may mean that wealth plans get scrapped because you have to pay off the debt first.
As you progress towards retirement age, the idea of reducing your working hours can be appealing, especially if you can do it without reducing your income. Fortunately, there is a way to do this. It’s called a Transition to Retirement Income Stream (TTRIS), which allows you to supplement your part-time income with regular payments from your superannuation savings.
Life does not always go to plan. Illness, job loss, accidents, or unexpected expenses can arrive without warning. While we cannot prevent these events, we can prepare for them. Having the right protections in place provides peace of mind and ensures your family is supported when life takes a turn.
There’s no shortage of financial advice out there. Everywhere you look—social media, news articles, investment forums—you’re bombarded with strategies, opinions, and predictions.
Despite the temporary, sudden downturns caused by the 2007-2009 global financial crisis and the 2020-2021 COVID pandemic, the value of the ASX increased by more than 160% between 2000 and 2024, as evidenced by the growth in the ASX 200 market index. This demonstrates that it’s better to invest in a variety of shares rather than sticking to just a few.
When most people think about retirement, they picture a dollar figure. How much super will I need? Do I have enough investments to last? While money is important, true retirement planning is about much more than a number on a page.
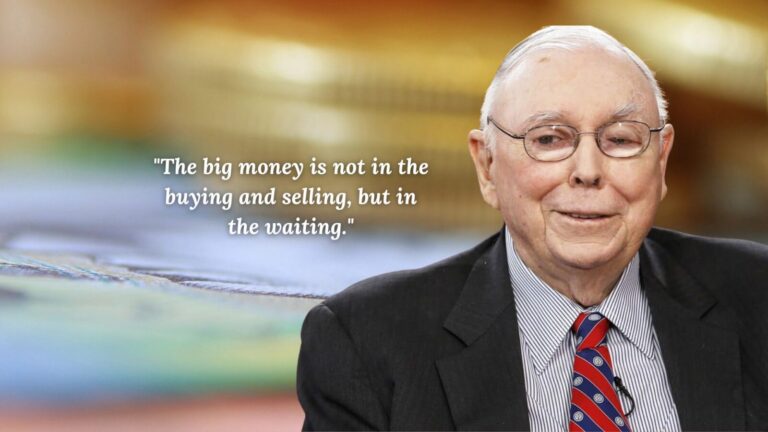
Discover why Charlie Munger’s quote, ‘The big money is not in the buying and selling, but in the waiting,’ holds the key to investment success through patience, compounding, and investor psychology.
Investing isn’t just about the numbers—far from it. Over my 26 years as a financial adviser and more than three decades as an investor, I’ve realized that understanding balance sheets,…
When it comes to money, it is often the small, consistent steps that make the biggest difference. You do not need to make dramatic changes overnight. Building good habits and sticking with them over time can transform your financial future.
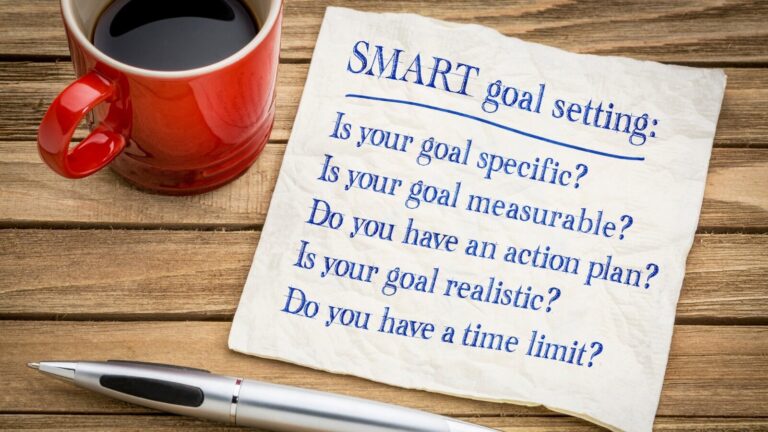
In the context of your personal finances, SMART refers to setting clear, quantifiable, feasible and appropriate financial objectives, to be carried out within a defined time frame. You’re much more likely to succeed if you avoid vague, non-measurable, unrealistic and inappropriate aims with no actual deadline. Relying on SMART goals will help you stay on track as you shape your financial future.
Over the last few years, I’ve taken on the management of many self-managed superannuation funds (SMSFs), and in doing so, I’ve encountered a particular investment type that often causes significant…
When we think about health, we often picture diet, exercise, or regular check-ups. What we do not always think about is money. Yet financial wellbeing and overall wellbeing are closely linked.
The opinion of many people towards debt can be best summed up in the often quoted line from Shakespeare, ‘neither a borrower nor a lender be.’ Yet others will embrace…
The idea of downsizing can be very appealing to empty-nesters. There will be less cleaning, gardening and maintenance, more time for hobbies and travel, and the icing on the cake comes if you can use the cash surplus you created to give your super a significant tax-effective boost.
But is the picture totally rosy, or are there some drawbacks to downsizing?
When it comes to money, more is not always better. Multiple super funds, a handful of bank accounts, different investment platforms, and stacks of paperwork can make it hard to see the bigger picture. Simplifying your finances can reduce stress and often leads to better results.
If you don’t feel prepared for retirement, you’re not alone.
Retirement preparedness doesn’t just mean having enough money to leave work but includes emotional challenges like your sense of self and what your future might look like.
Set yourself up for a rewarding retirement by meeting the following common challenges, head-on!
It is natural to want to enjoy the rewards of hard work. A new job, a pay rise, or a bonus can make it tempting to upgrade your car, move to a bigger house, or start spending more on dining and holidays. This is called lifestyle creep, and while it feels good in the short term, it can quietly slow down your long-term financial goals.
End of content
End of content