
Building a Strong Foundation: Avoiding Mortgage Default
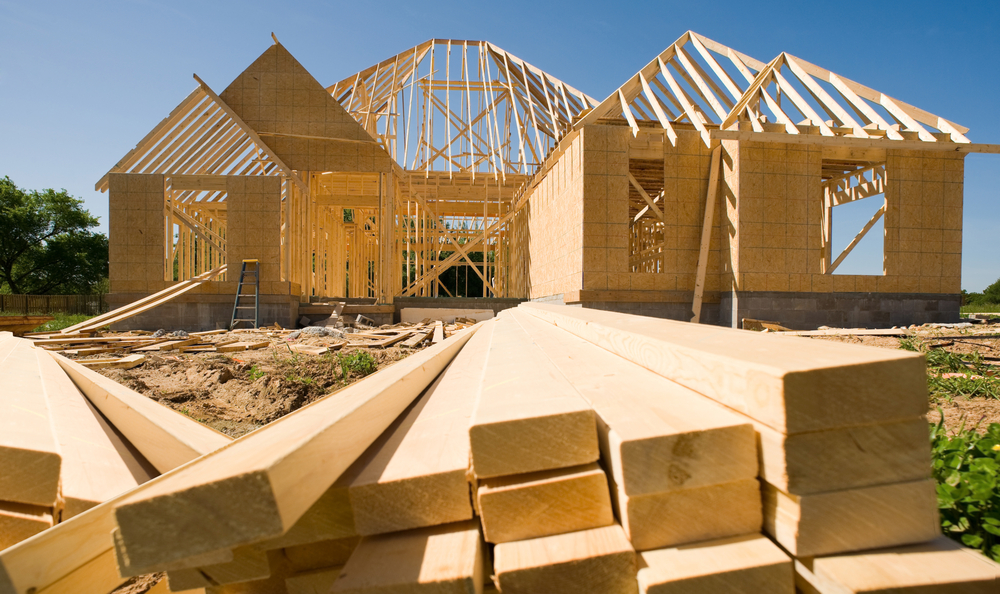
When building a home, it’s often said that the foundations are the most important part. Their primary purpose is to hold your house up – supporting the structure and preventing it from being affected by uneven ground.
Similarly, when purchasing a home and financing it with a mortgage, your financial foundation is just as crucial. A solid financial foundation can help you avoid mortgage stress, loan default, or even eviction.
Unfortunately, economic factors such as higher living expenses, interest rate hikes, or job loss can jeopardise your financial foundation.
What is mortgage stress?
Mortgage stress occurs when homeowners face difficulty meeting their mortgage repayments and their living expenses.
The Australian Bureau of Statistics has developed a “Mortgage Affordability Indicator”, which applies a 30% mortgage repayment threshold based on a household’s income.
Mortgage stress can cause immense strain on individuals and families and increase the risk of mortgage default.
Defaulting on a home loan happens when borrowers cannot make repayments as per the agreed terms and conditions of the loan agreement. This situation may result in serious consequences, including eviction and mortgagee possession of the property by the lender.
How to avoid mortgage stress and loan default
1. Know Your Financial Situation
One of the most crucial steps to avoid mortgage default is having a clear understanding of your financial situation.
By evaluating your income, expenses, and overall financial position, you can identify potential risks and understand what options are available to you.
Tracking your income and expenses will help you to analyse your spending habits and identify areas where you can cut back or make adjustments to free up cash flow. This is also a great time to review your expenses and renegotiate with service providers.
Reviewing your financial position may help you identify available options to assist in financial hardship.
2. Seek Professional Guidance
A mortgage broker can help you assess your current loan terms and explore options for refinancing or loan modifications that better align with your financial circumstances.
They can provide valuable advice and assist in negotiating more favourable terms with your lender.
3. Communicate with Your Lender
If you anticipate difficulties in making your mortgage repayments, it is best to communicate proactively with your lender in advance.
Most lenders have teams dedicated to supporting customers experiencing financial hardship. They may be able to offer temporary payment arrangements or alternative solutions to help you through a difficult period.
Case Study:
Consider the case of John and Sarah, a couple facing the risk of defaulting on their mortgage due to a sudden but temporary loss of income. To avoid this outcome, they took several steps:
Reviewed their financial situation –
John and Sarah underwent a complete review of their financial situation.
They reviewed their expenses, paused or cut back on discretionary spending, and renegotiated with all of their utility and service providers. This freed up cash flow to allocate towards their home loan.
They also identified that they were slightly ahead with their home loan repayments.
Communicated with their lender –
John and Sarah reached out to their lender to explore their loan repayment choices.
Since they had made some progress in their payments, they were eligible for a repayment holiday. This option would allow them to pay less towards their home loan for the next six months.
They had examined their financial situation and were confident that they could manage these reduced repayments, and this would give them six months to replace the lost income and get back on their feet.
To prevent mortgage stress and default, it’s important to actively manage your finances and have a clear understanding of your financial situation. Though it can be tough, taking early action and being transparent with your lender can help you work together to overcome financial challenges and ensure the safety of your home.
If you are facing any difficulties in making your mortgage payments, you can find helpful resources on the MoneySmart website: https://moneysmart.gov.au/.
The information provided in this article is general in nature only and does not constitute personal financial advice.