
Roadmap to retiring young
The dream of retiring young is one that captivates many peoples’ imaginations. The freedom to live life on your own terms, doing what you want, when you want is undeniably appealing, but is it attainable?
We say yes!
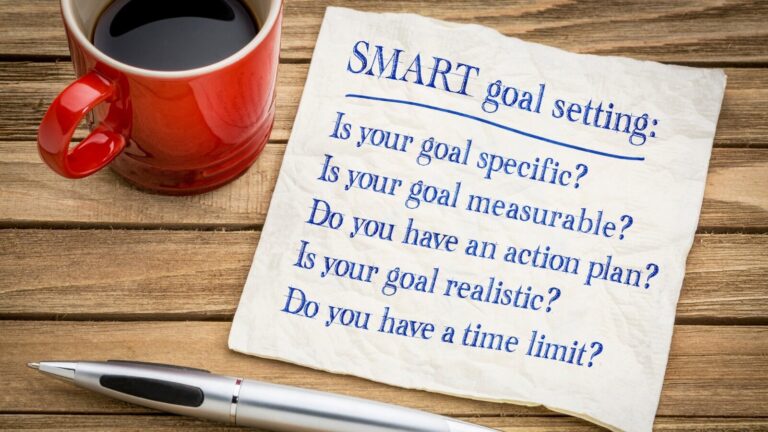
It doesn’t just happen, though. As with any goal, it takes planning and dedication along with a clear understanding of when and how you expect to achieve that goal.
Early retirement, as a concept, means different things to different people. Therefore, the first step on the road to your early retirement is to be clear about what it will look like, starting with:
- Timing: when do you want to retire?
- Lifestyle: what do you plan to do? Think travel, hobbies, daily activities, etc.
With an understanding of what retirement means to you, you can begin the process of charting a course to achieving it.
Develop a roadmap to early retirement by considering:
- Your current financial position
Conduct an audit of your income, expenses, assets and liabilities. Look at where your money is going and identify areas where you can cut back on unnecessary spending. This financial health assessment will help you determine how much money you need to live on weekly, monthly, yearly. It will form the basis of how much you’ll need to accumulate before you can retire.
This is important because under normal circumstances, you won’t have access to your superannuation savings until you reach your retirement age, as determined by government regulations. - Charting your journey
Having ascertained your retirement goals and your current financial position, now consider other points such as potential investment returns, tax, inflation, and how much to put aside to build a sufficient nest-egg.
A financial adviser will help you develop a comprehensive financial plan, tailored specifically for you, identifying clear financial milestones and outlining a roadmap for reaching them.
Over time, as goals evolve and circumstances change, your adviser can tweak your plan so you stay on track to achieve your early retirement goal. - Spending
A crucial step in the journey to early retirement is minimising unnecessary spending. Since you’ve already evaluated your spending habits, you’ve identified areas where you can cut back on spending without sacrificing your quality of life.
Be mindful of the difference between needs and wants, remembering that every dollar saved can be invested towards your early retirement.
When thinking about a purchase, ask yourself if the item is more important than the freedom of retiring young – keep your eyes on the end goal! - Diversified investments
Whether through real estate, stocks, or other investments that generate passive income, a varied portfolio will better support your retirement lifestyle during periods of economic fluctuation.
As you’ll still be obliged to submit an annual tax return, when developing an investment portfolio, tax minimisation should also be considered.
Your financial adviser will assist you to identify the most appropriate investment vehicles for you, and, as your retirement approaches, arrange an income stream that ensures your funds last the duration.
Attaining any financial goal requires discipline. Coach yourself to say ‘no’ to indulgences in the present, remembering that with the right roadmap and financial know-how, you really can make your dream of early retirement come true.
The information provided in this article is general in nature only and does not constitute personal financial advice.